Data Centre Boom: AEMO Sees 13% Grid Demand by 2036 [2026]
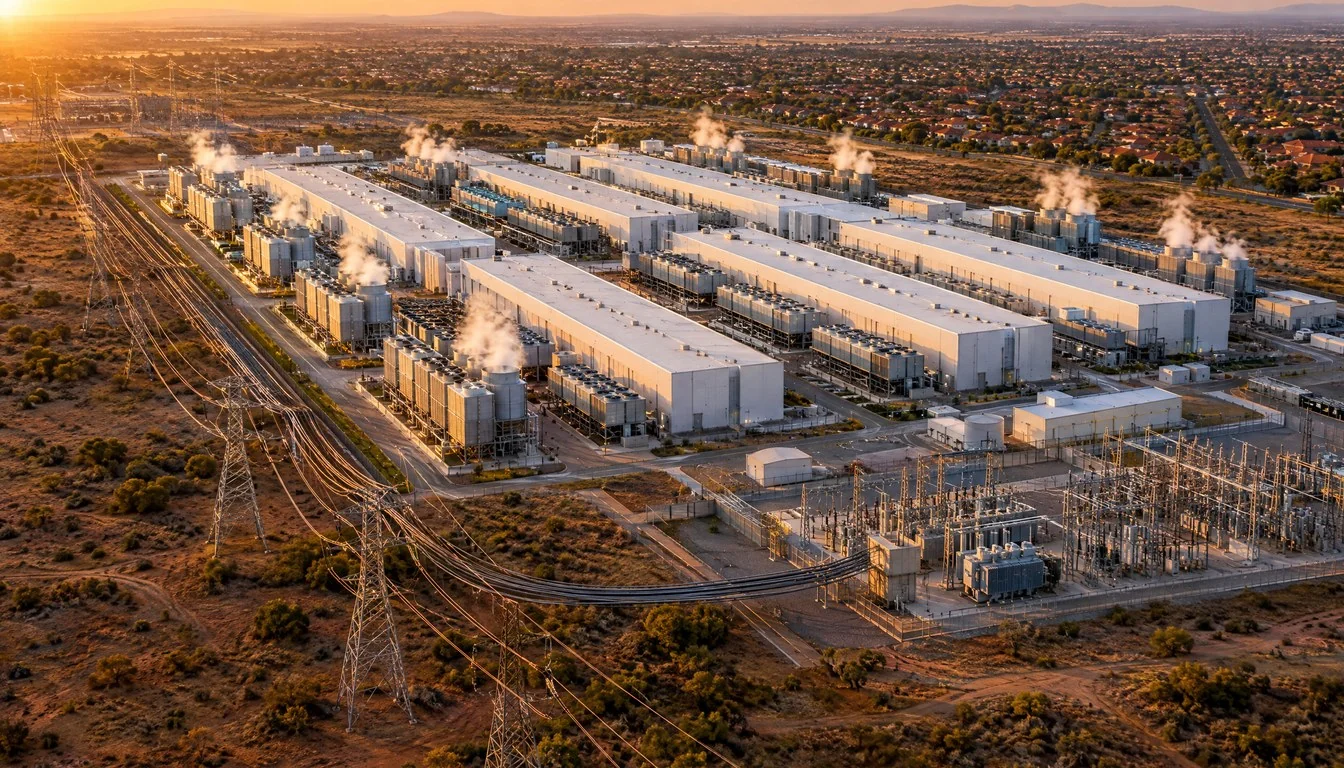
Australia’s electricity grid is bracing for a new kind of customer, one that never sleeps, never takes a public holiday, and draws power in a straight, unbroken line. The Australian Energy Market Operator (AEMO) now projects that data-centre energy demand nationwide could triple by 2030, a forecast that has pushed grid planners, state regulators and the federal government into the same uncomfortable conversation already playing out in Ireland, the United States and Singapore. The question driving that conversation is simple: can Australia build the generation, transmission and water infrastructure fast enough to host the artificial intelligence boom without handing households a bigger power bill in the process.
What makes the Australian case notable is timing. The country is watching the same pattern unfold overseas, in places where data-centre construction outpaced grid and community planning, and policymakers are explicitly trying to avoid repeating it. That is the core of the “three lessons” framing now circulating in energy and policy circles: demand can grow faster than supply, water consumption is an underpriced cost, and regulatory frameworks need to exist before shovels go into the ground, not after. Each of those lessons is backed by numbers AEMO, the Clean Energy Council and the Climate Council have already put on the record, and each carries direct consequences for electricity prices, water allocation and industrial policy through the next decade.
Don't miss new tech stories on Google
Add TrendinTech Australia once in the Google app and our stories appear in your news suggestions.
The Numbers Behind the Boom: What AEMO Is Forecasting
AEMO’s modelling is the anchor figure for almost every data centre energy demand story running in Australia this year. The market operator expects data centres to consume roughly 34 terawatt-hours (TWh) of electricity by 2036, a figure AEMO describes as nearly equivalent to the 38 TWh currently consumed by all households in New South Wales and Victoria combined. That comparison matters because it reframes the scale of the shift: a single category of industrial customer is on track to draw as much power as two of the country’s most populous states’ worth of homes.
Right now, data centres account for about 3% of the electricity supplied to Australia’s grid. AEMO’s central projection has that share climbing to 13% of power demand by 2036, even after the market operator factored in the high cancellation rate typical of early-stage data-centre projects. In other words, even with a healthy discount for proposals that never get built, the share of the grid dedicated to server halls and cooling systems is set to more than quadruple inside a decade. Oxford Economics Australia has produced a separate, longer-horizon estimate, forecasting the sector growing at roughly 25% annually and reaching 34.5 TWh by 2050, or about 12% of National Electricity Market energy. The two estimates use different methodologies and timeframes, but they land in a similar place: data centres are becoming a structural, not marginal, part of Australia’s energy mix.
Lesson One: Demand Can Outrun Supply
The first lesson is the most mechanical: electricity demand from data centres can scale faster than new generation, storage and transmission can be approved and built. The Clean Energy Council puts a number on this specifically, projecting Australian data-centre electricity demand rising from 1.35 gigawatts (GW) today to between 5 and 8 GW by 2035. That is not a gentle slope, it is a potential six-fold increase inside roughly nine years, concentrated in a handful of grid regions where developers have identified available land and transmission capacity.
Jackie Trad, CEO of the Clean Energy Council, frames the risk in plain terms: “Without new supplies of electricity to meet this demand, this will place increased pressure on all existing generation resources.” That is the crux of lesson one. New renewable generation, storage and network augmentation all run on multi-year approval and construction timelines, while a data centre campus can be permitted, built and energised in a fraction of that time once finance and hardware are secured. When the faster-moving load arrives before the slower-moving supply, the gap gets filled by whatever generation is already on the grid, typically the most expensive and often the most emissions-intensive capacity available at that moment, which flows straight through to wholesale prices.
Lesson Two: Water Is the Boom’s Quiet Cost
The second lesson gets less attention than electricity but carries its own strain on local infrastructure: water. Large, hyperscale-class data centres rely on evaporative cooling systems to manage the heat generated by dense racks of AI accelerators, and some facilities can consume up to 40 million litres of water per day, a volume described as equivalent to the daily usage of 80,000 households. That is a single site drawing on the same scale as a mid-sized regional town, every day, for the lifetime of the facility.
Water allocation is typically governed by state-level authorities and local catchment plans that were never designed with this class of industrial customer in mind. Unlike electricity, where new generation can theoretically be added to a shared grid, water is often a fixed, geographically bound resource. A data centre’s cooling demand competes directly with agriculture, residential supply and existing industry in the same catchment, and that competition becomes more visible in drought years. The lesson here, drawn from markets further along the data-centre build cycle such as Ireland, is that project approvals need water modelling with the same rigor applied to electricity connection agreements, not as an afterthought bolted on once construction is already underway.
Lesson Three: Frameworks Must Exist Before the Build-Out
The third lesson is regulatory, and it is the one Australian ministers have been most explicit about. Tim Ayres, Australia’s Minister for Industry and Innovation, has said the country has “learned lessons” from overseas, where data-centre development occurred “without an expectation and without a framework.” That phrasing is a direct acknowledgment that other markets allowed hyperscale construction to run ahead of planning rules, grid connection standards and community consultation processes, and then had to retrofit regulation onto an already-built industry.
Australia’s attempted correction is to build the expectation and the framework concurrently with the investment wave rather than after it. That includes conversations about whether data-centre operators should be required to bring their own new renewable generation to the grid rather than simply drawing on existing supply, a position the Clean Energy Council has pushed publicly. It also includes the kind of grid-planning work AEMO has been doing to model data-centre load growth years in advance, rather than reacting to connection applications as they land. Whether this concurrent approach actually holds up once the investment dollars start flowing at scale is the open question running through the rest of this decade.
The Three Lessons at a Glance
| Lesson | What It Means | Supporting Evidence |
|---|---|---|
| 1. Demand can outrun supply | National data centre energy demand could triple by 2030, faster than new generation and transmission can be approved | AEMO |
| 2. Water is a hidden cost | Large facilities can use up to 40 million litres of water per day, equivalent to 80,000 households | Climate Council |
| 3. Frameworks must precede build-out | Australia says it has “learned lessons” from markets that built first and regulated later | Minister Tim Ayres |
From 3% to 13%: How Data Centres Are Reshaping the Grid’s Share
It is worth sitting with the 3%-to-13% trajectory for a moment, because it is the single clearest data point describing how data centre energy demand is restructuring the National Electricity Market. A sector that today represents a relatively minor slice of grid consumption, comparable to several other large industrial categories, is forecast to become one of the two or three largest demand categories on the eastern seaboard grid within a decade. That is not a story about a niche technology sector growing at the margins, it is a story about a new anchor tenant arriving on a grid that was built and planned around a different demand profile.
The practical effect shows up in transmission planning. AEMO’s integrated system plan process has to account for where this new load will physically connect, because data centre energy demand is not evenly distributed. Developers cluster around existing transmission capacity, fibre routes and available land, which concentrates the grid impact in specific regions rather than spreading it evenly across the network. That clustering is part of why state-level planning bodies, not just the national market operator, are now central to how this demand gets absorbed.
The Price Tag: What the Climate Council Says About Power Bills
The Climate Council has put the sharpest number yet on what this could mean for household and business electricity bills. Its analysis warns that without sufficient new renewable generation and storage capacity, data centres could increase New South Wales power prices by 26% by 2035. That is not a projection of data-centre operators paying more for their own electricity, it is a projection of the price increase flowing to everyone else on the same grid, because added demand without added supply pushes up wholesale prices for the whole market, not just the new customer causing the demand.
That 26% figure is the clearest illustration of why the “bring your own generation” argument has gained traction among advocacy groups and some industry voices. If data-centre developers are required to fund new renewable capacity proportional to their own load, the theory goes, the price pressure on existing customers is contained because the new demand arrives with its own new supply attached. If that requirement does not materialise, or is watered down during negotiation, the Climate Council’s modelling suggests the price impact lands on households and small businesses who have no direct relationship with the data centre causing it.
Clean Energy Council: Industry Told to Power Itself
The Clean Energy Council’s position, delivered alongside its 1.35 GW-to-5-8 GW forecast, is that the data-centre sector should not simply be absorbed into existing generation plans as if it were ordinary load growth. Jackie Trad’s warning that “this will place increased pressure on all existing generation resources” is a direct argument for treating hyperscale data centres differently to a typical new industrial connection, precisely because of the scale and concentration involved.
This is also where the debate connects to the broader cloud computing industry that depends on this physical infrastructure. Every cloud storage and compute platform, from hyperscale public cloud providers down to specialised object storage services and backup providers, ultimately runs on physical data centres with the same electricity and water constraints discussed here. A policy requirement that large operators fund their own generation capacity would reshape the economics of running infrastructure in Australia, potentially raising the cost of hosting for providers that cannot amortise new generation investment across a large enough customer base.
Minister Tim Ayres on Avoiding Overseas Mistakes
Tim Ayres’ comments carry particular weight because he sits inside the federal government department responsible for industrial policy and innovation, the same portfolio negotiating with data-centre developers over investment conditions. His framing, that overseas development happened “without an expectation and without a framework,” is as much a statement about what Australia intends to require from developers as it is a historical observation about other markets.
The practical test of that statement will be whether Australia’s framework actually gets finalised and enforced before the bulk of the forecast capacity gets built, rather than during or after it, which is the exact sequencing failure the minister says other countries experienced. Given the Clean Energy Council’s own timeline points to most of the growth landing by 2035, and AEMO’s by 2036, the window for getting the framework in place before the majority of the capacity is energised is already narrowing.
What’s Actually Driving the Demand Surge
The underlying driver of all this data centre energy demand growth is the compute requirement of modern AI workloads, particularly training and running large language models. Each new generation of model, including locally-runnable systems such as DeepSeek V4.1 Flash, pushes more inference workload either onto cloud infrastructure or onto edge and local hardware, but the training runs behind these models still depend on concentrated clusters of accelerators housed in exactly the kind of power-hungry, water-intensive facilities driving AEMO’s forecasts.
That demand is not limited to AI training. General-purpose cloud growth, enterprise migration away from on-premises infrastructure, and the expansion of data sovereignty requirements that force multinational operators to build local capacity rather than serve Australian customers from overseas regions are all contributing load growth independent of the AI boom. The AI-specific demand is simply the fastest-growing and most visible component layered on top of an already-growing baseline.
Market Impact: Investment, Jobs and Grid Strain Collide
For the energy sector, the market impact of this data centre energy demand wave cuts two ways. On one hand, a guaranteed, large, long-term industrial customer is attractive to generation developers, because it can anchor investment in new wind, solar and storage projects that might otherwise struggle to secure financing without a committed buyer. On the other hand, if that new generation is not built in step with the data-centre load, the strain falls on the existing fleet, pushing up wholesale prices across the board as described in the Climate Council’s 26% warning.
There is also a security and resilience dimension to this build-out that is easy to overlook. Physical data centres hosting sensitive government, health and financial data become higher-value targets as they scale, and the sector’s growth is happening against a backdrop of major breaches already rattling Australian consumers, including the Oracle Health breach affecting nearly 20 million people. Resilience planning for new data-centre capacity increasingly has to account for cybersecurity posture, including identity and access controls such as those compared in debates over multi-factor authentication adoption, alongside the physical electricity and water questions dominating the current conversation.
Forecast Snapshot: The Key Figures Driving the Debate
| Source | Metric | Current / Baseline | Forecast | Target Year |
|---|---|---|---|---|
| AEMO | Share of national grid demand | 3% | 13% | 2036 |
| AEMO | Data centre annual energy consumption | — | 34 TWh | 2036 |
| AEMO | National data centre demand growth | — | Triples nationwide | 2030 |
| Clean Energy Council | Data centre electricity demand | 1.35 GW | 5–8 GW | 2035 |
| Oxford Economics Australia | Annual energy consumption / NEM share | — | 34.5 TWh (12% of NEM) | 2050 |
| Climate Council | NSW power price increase | — | Up to 26% | 2035 |
Historical Context: How We Got Here
Australia’s data centre sector has grown steadily for more than a decade on the back of enterprise cloud migration and local hosting requirements, but the scale of the current forecasts reflects a distinct new phase tied to generative AI. Earlier waves of data-centre construction were largely sized around conventional enterprise and cloud workloads, which scale in a far more predictable, linear fashion than the compute-intensive, power-dense clusters now being proposed for AI training and inference. Reports from outlets including the BBC have described this as a distinctly new category of industrial energy customer, one that energy and environmental experts argue the current grid, built around a different demand profile, has little spare capacity to absorb without new investment.
Australia is also able to draw on cautionary experience from markets that moved earlier. Ireland, in particular, has become a widely cited reference point, where local communities affected by the AI data-centre boom have described what has been characterised as cautionary tales for other countries weighing similar growth. That overseas experience is a large part of why Australian officials have been explicit about trying to build regulatory frameworks concurrently with investment, rather than retrofitting rules onto an industry that is already built out, as covered in reporting on the Irish experience.
Competitive Comparison: How the Debate Differs by Market
Every market grappling with data centre energy demand is working through some version of the same three lessons, but the policy responses differ. In Ireland, grid operators have in some cases restricted new data-centre connections in specific regions because local transmission capacity was already constrained, a more blunt intervention than anything currently proposed in Australia. In the United States, the debate has increasingly centered on utilities seeking to pass data-centre-driven infrastructure costs onto captive residential ratepayers, prompting state-level regulatory pushback in several jurisdictions. Singapore, by contrast, has at various points paused new data-centre approvals altogether while it recalibrated its energy and land-use planning, an approach more interventionist than Australia’s current preference for negotiated conditions on developers.
Australia’s approach, as described by Minister Ayres, sits somewhere between these positions: rather than an outright moratorium or a blunt connection cap, the stated intent is to attach conditions, such as co-funded renewable generation, to new developments while keeping the market broadly open to investment. Whether that middle path holds up once the Clean Energy Council’s forecast 5-8 GW of demand actually materialises is the test still to come.
Expert Voices on the Energy Crunch
Jackie Trad, CEO of the Clean Energy Council, has been the most direct public voice connecting the sector’s growth forecasts to grid risk: “Without new supplies of electricity to meet this demand, this will place increased pressure on all existing generation resources,” she said in comments accompanying the council’s proposal that data-centre developers contribute to new energy and skills capacity.
Energy analysts tracking where new facilities are being sited have pointed to Australia’s lack of surplus grid capacity as the defining constraint shaping developer behaviour. James Murphy, an analyst at data-centre market tracker DC Byte, has observed that in a market like Australia, where there isn’t a surplus of energy in the grid, developers “must be innovative and identify areas where power is available,” a dynamic discussed in an ABC News interview on why large AI data centres are increasingly being proposed for regional rather than metropolitan sites. Energy commentator Ted O’Connor, in the same discussion, noted simply that these modern data centres require immense quantities of electricity, underscoring why siting decisions are now driven as much by grid headroom as by land cost or connectivity.
On the policy side, Minister Tim Ayres has warned that large new loads arriving faster than generation and transmission can expand risk pushing up prices for everyone if the growth is not carefully managed, a concern echoed in financial circles. Ian Learmonth, CEO of the Clean Energy Finance Corporation, has pointed to data-centre electricity demand representing as much as 8 to 11% of Australia’s projected electricity consumption by 2035, alongside up to 135 billion Australian dollars in associated data-centre investment, a figure he cited in the foreword to a report on data-centre electricity demand, investment and potential price impacts carried by the ABC.
Predictions: What Happens Next Through 2036
- Co-funding requirements become standard practice. Expect more Australian states to formally attach renewable co-investment conditions to large data-centre connection approvals, following the model the Clean Energy Council is already pushing.
- Regional siting accelerates. As transmission capacity near major cities tightens, more large facilities will be proposed in regional areas with existing or planned renewable generation nearby, continuing the pattern analysts have already flagged.
- Water modelling gets formalised. Given the scale of daily water use at large sites, expect state water authorities to introduce dedicated assessment pathways for data-centre cooling demand rather than treating it as generic industrial water use.
- Price-impact scrutiny intensifies. With the Climate Council’s 26% NSW price warning now on the public record, expect energy regulators to face growing pressure to publish clearer modelling of how much of any future price rise is directly attributable to data-centre load.
- The AEMO 13% figure becomes a recurring benchmark. Expect the 3%-to-13% grid-share trajectory to become the standard reference point cited in future policy debates, similar to how specific emissions or renewable-share targets have anchored past energy debates.
Why This Matters Beyond the Energy Sector
The data centre energy demand debate is ultimately a proxy for a much bigger question about how Australia wants to host the digital and AI economy. Every cloud platform, every enterprise migrating workloads offshore or onshore, and every service built on top of cloud infrastructure has a stake in whether this build-out happens smoothly or becomes a source of recurring price shocks and community opposition, the kind already visible in some overseas markets according to the World Economic Forum’s analysis of managing data-centre energy and water use in the AI era.
AEMO itself has framed the planning challenge in terms that go beyond simply adding more generation. In a speech on the subject, the market operator argued that planners need to account for the characteristics of the demand, not just its size, and avoid mistaking a technical integration challenge for an insurmountable one, while ensuring the regulatory framework evolves alongside the participants in the system, comments delivered in a speech on aligning energy policy with grid capacity and infrastructure planning. That framing, treating this as a solvable planning problem rather than an unmanageable crisis, is effectively the thesis behind all three lessons discussed above.
The Bottom Line for Households and Businesses
For ordinary electricity customers, the practical takeaway from this wave of forecasts is that data centre energy demand is no longer a background industry trend, it is now a direct input into how much households and businesses pay for power over the next decade. The gap between AEMO’s 13% grid-share projection and the Climate Council’s 26% price-increase warning represents the range of outcomes Australia is choosing between right now, largely through decisions being made about co-investment requirements, water allocation rules and transmission planning today. According to the Australian Associated Press, that tension was explicitly raised during a recent parliamentary inquiry warning that households and businesses should not have to pay more simply to accommodate power-hungry data centres relocating into their neighbourhoods.
Whether Australia lands closer to the more optimistic co-investment scenario or the higher-price outcome will likely become clear well before 2036, since most of the forecast capacity additions are expected between now and 2035. That makes the next two to three years, not the headline 2036 target date, the period that will actually determine which of the three lessons Australia manages to apply and which it repeats.
Frequently Asked Questions
How much could data centre energy demand grow in Australia?
AEMO projects that data-centre energy demand nationwide could triple by 2030, with consumption reaching about 34 TWh by 2036, close to the 38 TWh currently used by all households in New South Wales and Victoria combined.
What share of Australia’s electricity grid do data centres currently use?
Data centres currently account for about 3% of electricity supplied to Australia’s grid. AEMO projects this could rise to 13% of power demand by 2036.
Could data centres push up electricity prices for households?
The Climate Council has warned that without sufficient new renewable generation and storage, data centres could increase New South Wales power prices by up to 26% by 2035 if the added demand is not matched by added supply.
Why do data centres use so much water?
Many large facilities rely on evaporative cooling to manage heat from dense computing hardware. Some data centres can consume up to 40 million litres of water per day, roughly equivalent to the daily usage of 80,000 households.
What is the Clean Energy Council’s forecast for data centre electricity demand?
The Clean Energy Council expects Australian data-centre electricity demand to rise from 1.35 GW today to between 5 and 8 GW by 2035, and has called for developers to help fund new generation capacity.
What lessons is Australia trying to apply from overseas data centre growth?
Minister for Industry and Innovation Tim Ayres has said Australia has learned lessons from overseas markets where data-centre development occurred without an expectation or a regulatory framework, and is trying to build conditions for developers concurrently with investment rather than afterward.
How does Oxford Economics Australia’s forecast differ from AEMO’s?
Oxford Economics Australia projects data-centre growth of around 25% annually, reaching 34.5 TWh of consumption by 2050, or about 12% of National Electricity Market energy, a longer-horizon estimate than AEMO’s 2036 projection but pointing in a similar direction.
Is the data centre energy demand surge mainly driven by AI?
AI training and inference workloads are the fastest-growing component, but general cloud migration and data sovereignty requirements that push multinational operators to build local capacity are also contributing to the overall growth in data centre energy demand.
Related Coverage
Tahlia Rourke
Tahlia Rourke is the Cloud & Software Reporter at TrendinTech, where she covers cloud infrastructure, enterprise platforms, software development and the digital transformation of Australian businesses. She is particularly interested in what happens after the contract is signed: the migrations that overrun, the bills that surprise and the teams that make it work.
All stories by Tahlia Rourke (3)