Morgan Stanley Sees 85% SpaceX Upside on Flight 15 [2026]
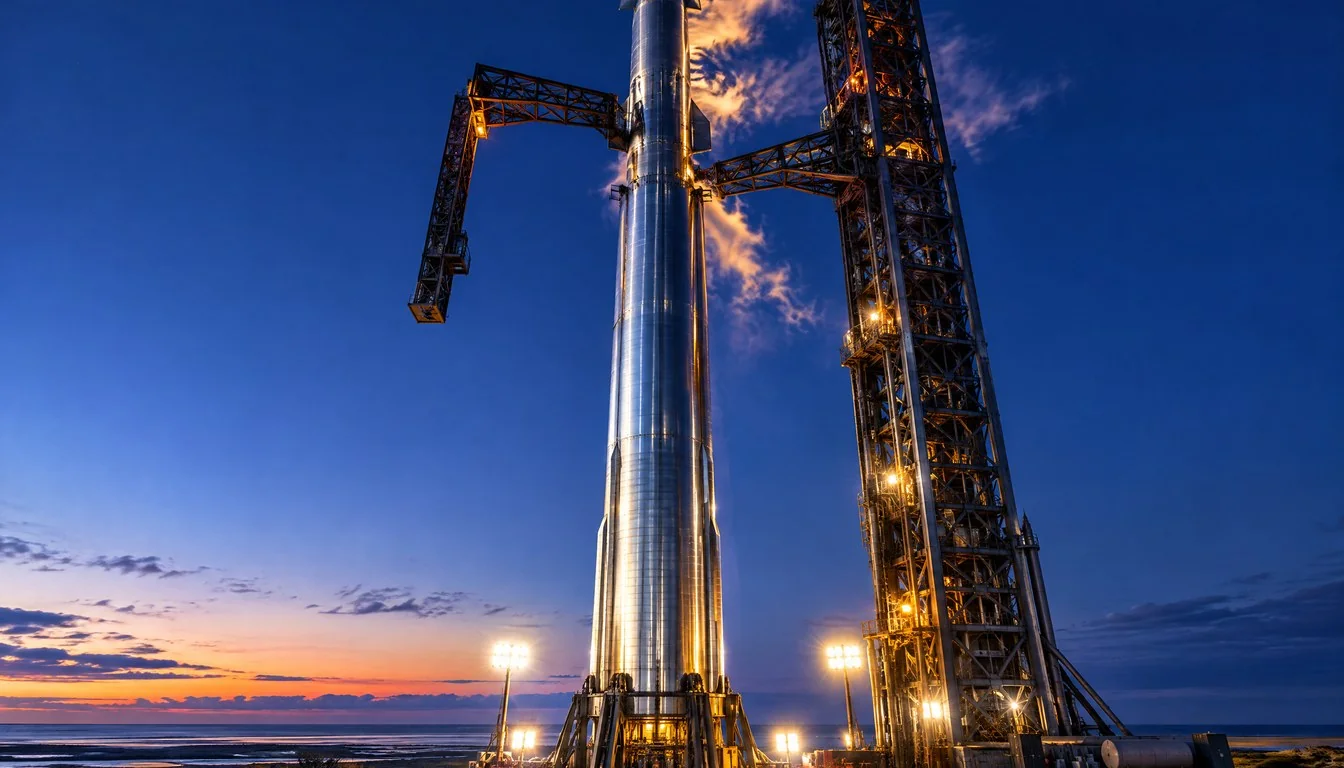
Morgan Stanley is telling clients that SpaceX stock looks mispriced heading into the company’s next big rocket test. In a research note cited by Seeking Alpha and TradingView on October 12, 2026, the bank reiterated an Overweight rating on SpaceX (SPCX:NASDAQ) and a $300 price target, implying roughly 85% upside from the October 9 closing price of $162.57. The catalyst the bank is watching most closely: Starship Flight 15, the next test of the vehicle SpaceX needs to make fully reusable if it wants to scale Starlink, cut launch costs, and chase a slice of the AI infrastructure boom.
The call matters beyond the ticker symbol. SpaceX is one of the most closely watched private companies in tech, and Morgan Stanley’s note links its valuation directly to hardware milestones happening in near real time this fall. For readers tracking the SpaceX stock price target story, the Starship Flight 15 launch window, or how satellite bandwidth economics intersect with the AI data center buildout, this is the clearest signal yet of where Wall Street sees the next leg of value creation.
Don't miss new tech stories on Google
Add TrendinTech once in the Google app and our stories appear in your news suggestions.
Morgan Stanley’s $300 Price Target: Breaking Down the Math
Morgan Stanley’s note, authored by analyst Adam Jonas, reaffirmed a $300 price target against an October 9, 2026 closing price of $162.57. That spread works out to approximately 85% implied upside, a figure that stands out even by the standards of a bank known for bullish space-sector calls. The rating itself is unchanged: Overweight, the same stance Morgan Stanley has held through much of SpaceX’s recent run as a company whose shares still trade actively enough to generate a tracked price.
What changed is the framing. Rather than pointing to a single number, Jonas’s note ties the valuation gap to a cluster of near-term catalysts: Starship’s development trajectory, unreleased AI products, and new cloud-infrastructure contracts that the bank estimates could be priced in the range of $30 to $50 per watt, per the Yahoo Finance recap of the report. That per-watt figure is a detail worth sitting with, because it signals Morgan Stanley views SpaceX less as a pure launch company now and more as an emerging player in the compute-and-power stack that AI companies are racing to secure.
Adam Jonas has been explicit about why he thinks the market is underpricing the stock right now. In a note reported by Business Insider, he described the period ahead of Flight 15 as a window where “investors can take advantage of a unique opportunity to buy shares that look unusually cheap.” That kind of language from a four-star-rated analyst, as MarketBeat characterizes Jonas’s track record, tends to move sentiment even before the underlying catalyst actually happens.
Why Starship Flight 15 Is the Catalyst Everyone’s Watching
Starship is SpaceX’s next-generation launch system, the vehicle meant to eventually replace Falcon 9 for the heaviest and most frequent missions. It is also the piece of hardware standing between SpaceX’s current cost structure and the step-change in launch economics that would make satellite internet, in-space manufacturing, and eventually crewed Mars missions financially viable at scale. Flight 15 is the next scheduled test in that program, and according to the Yahoo Finance report on Morgan Stanley’s note, it is expected sometime in “late October or early November,” though no exact date has been confirmed publicly.
Morgan Stanley’s note frames two specific milestones as the ones that matter most for the stock: a successful recovery of both the spacecraft and the booster during a single flight, and a subsequent flight using reused V3 hardware. Neither of those outcomes has happened yet on a Starship test, which is exactly why the bank is calling the flight a catalyst rather than a formality. A rocket company only earns a reusability premium once it has actually demonstrated reusability under real flight conditions, not in a simulation or a press release.
It’s worth being precise about what is confirmed here. Several outlets have described a possible “ship catch,” where the returning Starship vehicle would be captured directly by the launch tower’s recovery arms rather than landing independently. That detail appears in secondary reporting, but Morgan Stanley’s own note does not treat it as locked in, and SpaceX has not published a flight plan confirming it. Treat any claim of a guaranteed catch, or guaranteed full recovery of both vehicles, as unconfirmed until SpaceX says otherwise.
The V3 Hardware Question
The mention of “V3 hardware” signals that Morgan Stanley is tracking SpaceX’s iterative design cycle closely. Each Starship version has brought changes to the heat shield, engine configuration, and propellant management, pushing the vehicle closer to airline-style reusability, where a booster and ship fly, land, get refurbished, and fly again within days rather than months. Reusing V3 hardware on a flight after Flight 15 would be the first hard evidence that SpaceX’s reuse cadence is accelerating rather than just theoretically possible.
Starlink Bandwidth Economics: The Hidden Catalyst in the Note
One of the more striking figures in Morgan Stanley’s analysis, as reported by Yahoo Finance, concerns Starlink capacity rather than the rocket itself. The bank estimates that a single Starship launch carrying next-generation Starlink satellites could deliver bandwidth capacity equivalent to between one and more than two months of what SpaceX currently deploys through its Falcon 9 missions. That is a meaningful claim: it suggests Starship’s real financial upside isn’t just cheaper launches, it’s a step-function increase in how fast SpaceX can scale its own satellite internet constellation, which is already one of its largest revenue lines. Starlink’s physical footprint has also made headlines for less flattering reasons recently, including the ground-station fire incident in Poland that drew international attention to the hardware behind the network.
Falcon 9 has been the workhorse of the Starlink rollout for years, launching batches of satellites on a near-weekly cadence. Starship’s larger payload fairing and greater lift capacity mean each launch could carry substantially more next-generation satellites, each of which is reportedly more capable than the units flying today. If Morgan Stanley’s one-to-two-month equivalence estimate holds up once Starship reaches operational cadence, it would reshape how fast SpaceX can expand Starlink coverage and capacity in markets where demand is outstripping supply, including rural broadband and in-flight connectivity deals.
This bandwidth math is also why Wall Street keeps describing SpaceX in the same breath as the broader AI infrastructure story. Satellite connectivity is increasingly discussed as a complement to terrestrial data center buildouts, particularly for edge connectivity and remote compute access. A faster Starlink rollout does not replace fiber or data center capacity, but it does extend the reach of whatever compute and AI services SpaceX or its partners end up offering in markets that traditional infrastructure hasn’t reached yet. That infrastructure backdrop is the same one playing out on the ground, where regulators are moving to track AI-driven power demand, including FERC’s recent approval of PJM’s data center registry.
The AI and Cloud Infrastructure Angle
Morgan Stanley’s note explicitly lists “future AI product releases” and “additional cloud-infrastructure contracts” as catalysts sitting alongside Starship development, according to Yahoo Finance’s coverage of the report. That is notable framing for a company most people still associate primarily with rockets and satellites. It suggests Morgan Stanley sees SpaceX positioning itself inside the same compute-and-power conversation that is currently driving valuations across the AI sector, from chipmakers to hyperscale cloud providers.
The $30-to-$50-per-watt pricing range the bank cites for potential cloud-infrastructure contracts is a figure worth comparing against the broader AI data center buildout. Power availability has become the binding constraint for new AI compute capacity across the industry, with utilities and grid operators from Texas to Virginia racing to interconnect new facilities fast enough to keep up with demand. If SpaceX is positioning any of its infrastructure, satellite ground stations, or power assets to be priced into that market, it would represent a genuinely new revenue category for the company, separate from launch services and Starlink subscriptions.
Adam Jonas put this dynamic in blunt terms in a note cited by CNBC, arguing that “adjusted for growth, SpaceX is one of the cheaper ways to play the strong optionality of the Space and Intelligence Economy.” That phrase, pairing space with the AI-driven “intelligence economy,” is the clearest articulation yet of how Morgan Stanley is pricing SpaceX: not as a rocket company with a side business, but as a diversified infrastructure play where launch, satellites, power, and AI compute all feed into the same long-term thesis.
Market Reaction and Investor Sentiment
SpaceX shares have responded to the renewed bullish coverage. A report from The Herald Business noted shares surged 7% after Morgan Stanley reaffirmed its $300 target, with the outlet citing a 75% upside figure in its own calculation, a close variant of the roughly 85% figure tied to the October 9 close reported elsewhere. The gap between those two upside figures simply reflects which reference price each outlet used on which day, underscoring how fast sentiment and quoted levels are moving around this stock in the run-up to Flight 15.
MarketBeat’s sentiment tracking describes the broader mood around SpaceX stock as leaning positive heading into the test, with commentary suggesting Starship is “becoming a major catalyst” for the name. That optimism stands out against a messier week for tech equities broadly, where tech stocks have been weighed down by oil prices spiking past $107 a barrel amid geopolitical tension. That kind of sentiment shift is common ahead of binary technical milestones in the space sector: investors tend to price in optimism before a launch and then react sharply, in either direction, once the actual flight data comes in. Previous Starship tests have produced exactly that pattern, with shares and sentiment swinging on outcomes that were only confirmed once telemetry and recovery data came back.
| Metric | Figure | Source |
|---|---|---|
| Rating | Overweight | Morgan Stanley (Adam Jonas) |
| Price target | $300 per share | Morgan Stanley |
| Reference close | $162.57 (Oct. 9, 2026) | Seeking Alpha / TradingView |
| Implied upside | ~85% | Morgan Stanley note |
| Reported share move post-note | +7% | The Herald Business |
| Cloud-infrastructure contract pricing estimate | $30–$50 per watt | Morgan Stanley (via Yahoo Finance) |
| Starlink bandwidth equivalence per Starship launch | 1 to 2+ months of current Falcon 9 capacity | Morgan Stanley (via Yahoo Finance) |
Historical Context: From Falcon 9 to Full Reusability
SpaceX built its commercial dominance on Falcon 9’s partial reusability, landing and reflying boosters while still expending the upper stage on every mission. That innovation alone cut launch costs enough to make SpaceX the default launch provider for commercial satellite operators, government payloads, and crewed missions to the International Space Station. Starship represents the next step in that same logic, applied to a much larger vehicle: full reusability of both stages, higher payload capacity, and a design intended to support everything from Starlink deployment to lunar and Mars missions under NASA’s Artemis program.
Getting there has not been linear. Starship’s test program has included vehicles that reached orbital velocity and vehicles that did not survive reentry, a normal pattern for an iterative flight-test development approach that prioritizes fast learning cycles over guaranteed success on every attempt. MarketBeat’s sentiment coverage notes that an earlier flight in the program reportedly achieved the program’s first successful orbital entry, a milestone that itself took years of iteration to reach. Flight 15 sits on top of that accumulated progress, which is part of why Morgan Stanley is treating it as a higher-stakes test than a routine launch.
That history matters for anyone sizing up the current price target call. The stock’s valuation has tended to move with real flight-test outcomes more than with broader market conditions. A clean Flight 15, by Morgan Stanley’s own framing, would be read as validation of the reusability thesis; a setback would likely push the valuation conversation back by months.
Competitive Landscape: SpaceX, Blue Origin, and the Launch Market
SpaceX’s current market position is unusual for a sector that, on paper, has several credible competitors. Blue Origin has continued developing its own heavy-lift New Glenn rocket, and United Launch Alliance remains the primary government-preferred alternative for national security payloads. Neither company, based on public reporting, has demonstrated a fully reusable orbital-class vehicle at the scale Starship is attempting, which is a large part of why Morgan Stanley’s note treats SpaceX’s reusability progress as a company-specific catalyst rather than an industry-wide trend it has to share credit for.
The competitive gap extends to Starlink as well. Amazon’s Kuiper constellation and other low-earth-orbit broadband projects are still scaling toward the coverage SpaceX has already built, giving SpaceX a head start in both subscriber base and launch cadence. Morgan Stanley’s bandwidth-equivalence estimate for Flight 15 is really a comment on how much further ahead SpaceX could pull once Starship starts carrying Starlink payloads at scale.
This is also where the AI infrastructure framing becomes a genuine point of differentiation rather than marketing language. Traditional launch competitors are not positioning themselves as power or compute infrastructure providers, even as other hardware-heavy suppliers pivot toward AI demand, as seen with Taiwan’s ProLogium shifting roughly half its sales toward AI data centers as aerospace and EV demand cools. If SpaceX’s cloud-infrastructure contract ambitions, priced in the $30-to-$50-per-watt range Morgan Stanley cites, actually materialize, the company would be competing in an entirely different market from Blue Origin or ULA, one closer to the data center and power-generation companies currently benefiting from the AI buildout than to traditional aerospace primes.
What’s Confirmed and What Isn’t
Given how fast this story is moving, it’s worth separating the confirmed details from the parts still circulating as unverified claims. Confirmed, per Seeking Alpha and TradingView’s reporting on the Morgan Stanley note: the Overweight rating, the $300 price target, the $162.57 reference close on October 9, 2026, and the roughly 85% implied upside tied to that price. Also confirmed: Morgan Stanley’s identification of Starship development, AI product releases, and cloud-infrastructure contracts as the catalysts behind the call, along with the specific $30-to-$50-per-watt and one-to-two-month bandwidth figures reported by Yahoo Finance.
Unconfirmed: the exact launch date for Starship Flight 15. Different reports describe the timing as “about one month” out or “late October or early November,” but no single confirmed date has been published by SpaceX. Also unconfirmed: whether Flight 15 will actually achieve a successful catch or recovery of both the spacecraft and booster, or whether a subsequent flight will fly on reused V3 hardware as planned. Those are the outcomes Morgan Stanley is betting on, not outcomes it is reporting as already achieved. Readers should treat the “SPCX:NASDAQ” ticker label itself with the same caution; SpaceX’s publicly tracked share price reflects private-market and secondary trading activity rather than a traditional public listing.
Why the Distinction Matters for Investors
Price targets built around a binary technical test carry a different risk profile than targets built on recurring revenue growth. If Flight 15 slips further, or if the recovery attempt fails, Morgan Stanley’s timeline for closing the gap between $162.57 and $300 would almost certainly extend. The bank’s own language, framing the next few weeks as a buying window “ahead of Starship Flight 15,” only holds if the flight happens roughly on the schedule implied in current reporting.
Expert Commentary: What Morgan Stanley’s Analyst Is Saying
Adam Jonas, the Morgan Stanley analyst behind the note, has been unusually direct about the stakes of this specific flight. He described Flight 15 as shaping up to be SpaceX’s “biggest test towards Starship reusability since the IPO,” according to a note reported by Business Insider. That comparison point, to the company’s own IPO, signals just how significant Jonas views this test relative to the rest of SpaceX’s corporate milestones.
Jonas also flagged what comes after Flight 15. In the same note covered by Business Insider, he pointed to “Flight 16, targeted before year-end, [as] potentially an even bigger one,” suggesting Morgan Stanley views the current test as part of a sequence of catalysts rather than a single make-or-break event. That framing gives the bank’s thesis some cushion: even if Flight 15 doesn’t deliver a clean result, the note implies the bigger validation moment could still be ahead.
On valuation specifically, Jonas argued that the weeks before the flight represent a mispricing opportunity. In commentary shared publicly and reported via a post from Sawyer Merritt, Jonas wrote that “we think that over the next few weeks (ahead of Starship Flight 15), investors can take advantage of a unique opportunity to buy shares that look unusually cheap.” In the same note, he added that “we expect developments over the next few months will help investors better appreciate the role of SPCX in addressing the critical bottlenecks of power and chip making, potentially unlocking earnings growth and multiple expansion for the stock.”
Jonas’s broader thesis, as relayed by CNBC, ties SpaceX’s valuation to the same “Space and Intelligence Economy” language that is showing up across Wall Street coverage of AI infrastructure plays. He noted that “adjusted for growth, SpaceX is one of the cheaper ways to play the strong optionality of the Space and Intelligence Economy,” positioning the stock less as a rocket-launch bet and more as a diversified claim on the compute, power, and connectivity buildout driving the rest of the tech sector.
Catalysts Timeline: What to Watch and When
| Catalyst | Expected Window | Why It Matters |
|---|---|---|
| Starship Flight 15 | Late October–early November 2026 (unconfirmed exact date) | Tests recovery of spacecraft and booster; key reusability milestone |
| Starship Flight 16 | Before year-end 2026 (per Morgan Stanley note) | Flagged by Jonas as potentially an even bigger catalyst than Flight 15 |
| Reused V3 hardware flight | Following a successful Flight 15 recovery | Would confirm faster reuse cadence, core to the cost-reduction thesis |
| Next-gen Starlink satellite deployment via Starship | Contingent on Starship reaching operational cadence | Could add 1–2+ months of current Falcon 9 bandwidth capacity per launch |
| New cloud-infrastructure contracts | Not yet dated; described as a forward catalyst | Estimated at $30–$50 per watt; ties SpaceX to AI power/compute demand |
Market Impact Beyond SpaceX
A successful Flight 15 would ripple beyond SpaceX’s own valuation. Satellite operators, launch customers, and insurers who price risk on Starship-dependent missions would get a clearer signal about when full reusability actually arrives rather than when it’s promised. Government customers, including NASA’s Artemis program, have mission timelines tied partly to Starship’s development pace, so a confirmed recovery milestone would matter well outside equity research notes.
There is also a read-through for the AI infrastructure sector broadly. If Morgan Stanley’s framing of SpaceX as a cloud-infrastructure and power player gains traction, it adds another well-capitalized competitor to a market already crowded with hyperscalers and specialized data center operators racing to secure power capacity, the same scramble for compute capacity that has pushed GPU makers to redirect flagship silicon like Nvidia’s GB202 away from consumer cards and toward RTX Pro and data center demand. That dynamic connects directly to the broader scramble over grid interconnection and power pricing that has been playing out across the AI data center buildout this year, where companies are increasingly willing to pay a premium for guaranteed power access regardless of the source.
Predictions: What Happens Next
- Flight 15 timing slips again. Given the pattern of delayed Starship test dates reported across outlets, a further push into November or beyond is plausible, and would likely cap near-term upside in the stock regardless of the underlying $300 target.
- A partial success gets priced as a win. If SpaceX recovers one vehicle (ship or booster) but not both, expect bullish coverage to still frame it as meaningful progress, even though Morgan Stanley’s stated milestone requires both.
- Cloud-infrastructure contract details emerge before Flight 16. Given how specifically Morgan Stanley priced the $30-to-$50-per-watt opportunity, expect more concrete reporting on what those contracts actually involve within the next quarter.
- Other analysts follow with updated targets. Bullish bank notes tend to cluster; if Flight 15 goes well, expect additional price-target revisions from other coverage of SPCX in the weeks that follow.
- Starlink capacity claims get tested against real deployment data. The one-to-two-month bandwidth equivalence figure is an estimate, not a demonstrated outcome, and will be scrutinized once SpaceX actually flies a Starship-launched Starlink batch.
Risks to the Bullish Thesis
The most direct risk is the most obvious one: Starship test flights have not always gone as planned, and a failed or partial recovery attempt on Flight 15 would undercut the near-term catalyst the entire note is built around. Because the bank’s upside case leans heavily on rocket hardware performing on a specific, still-unconfirmed schedule, the thesis is more binary than a typical earnings-driven price target.
There is also execution risk on the newer parts of the thesis: the AI product releases and cloud-infrastructure contracts Morgan Stanley flags. Those are future catalysts rather than signed deals, and the $30-to-$50-per-watt figure is an estimate of pricing, not a confirmed contract value. Any delay in SpaceX closing deals in that category would remove one of the two non-Starship pillars supporting the $300 target.
Related
- Poland Starlink Fire: Germany Detains 2 Turks [2026]
- Tech Stocks Weigh on Wall St as Oil Hits $107 [2026]
- FERC Approves PJM’s 50MW Data Center Registry [2026]
- Taiwan’s ProLogium Pivots Half of Sales to AI Data Centers [2026]
- NVIDIA Pulls RTX 5090, Shifts GB202 to RTX Pro [2026]
Frequently Asked Questions
What did Morgan Stanley say about SpaceX stock?
Morgan Stanley reiterated an Overweight rating on SpaceX (SPCX:NASDAQ) with a $300 price target, implying approximately 85% upside from the October 9, 2026 closing price of $162.57, according to Seeking Alpha and TradingView. Analyst Adam Jonas cited Starship Flight 15, future AI product releases, and new cloud-infrastructure contracts as the key catalysts behind the call.
When is SpaceX’s Starship Flight 15 launching?
No exact date has been confirmed. Reports describe the timing variously as “about one month” out or “late October or early November,” based on coverage cited by Yahoo Finance. SpaceX has not published an official confirmed launch date for Flight 15 as of this writing.
Why is Starship Flight 15 considered such an important test?
Morgan Stanley’s note identifies the successful recovery of both the spacecraft and the booster during a single flight, followed by reuse of V3 hardware, as the key milestones. Those outcomes would represent a significant step toward full Starship reusability, which underpins SpaceX’s long-term cost structure for Starlink deployment and future missions.
Has Starship successfully achieved full reusability before?
Not based on confirmed public reporting. Full recovery of both the spacecraft and booster on a single flight, followed by a subsequent flight on reused hardware, is the milestone Morgan Stanley is watching for with Flight 15, not an outcome that has already been confirmed on a prior test.
How does Starship connect to SpaceX’s Starlink business?
Morgan Stanley estimates that a single Starship launch carrying next-generation Starlink satellites could deliver bandwidth capacity equivalent to one to more than two months of what SpaceX currently deploys through Falcon 9 missions, according to Yahoo Finance’s coverage of the note. That would let SpaceX scale Starlink coverage and capacity considerably faster than its current launch cadence allows.
What does the $30 to $50 per watt figure refer to?
It is Morgan Stanley’s estimate of the pricing range for potential future cloud-infrastructure contracts that SpaceX could pursue, tying the company to the broader AI compute and power market rather than just launch services and satellite internet.
Is SpaceX stock publicly traded on NASDAQ?
SpaceX’s share price is tracked under the SPCX label across financial sites including Seeking Alpha, TradingView, and MarketBeat, reflecting secondary and private-market trading activity. Whether this constitutes a fully confirmed, traditional NASDAQ public listing is not something this report independently verifies; readers should treat the ticker formatting as reported by these outlets rather than as confirmed exchange-listing status.
What happens to the price target if Flight 15 fails or slips?
Morgan Stanley’s note does not specify a contingency target. Given that the bank explicitly frames Flight 15 as a near-term catalyst for closing the valuation gap, a failed recovery attempt or a significant further delay would likely push back the timeline for the stock to re-rate toward the $300 target, even if the long-term Overweight thesis remains intact.
Related Coverage
Owen Castellanos
Owen Castellanos is the Hardware & Gaming Reporter at TrendinTech, where he tests graphics cards, processors, consoles and peripherals and follows the games industry, from the major publishers to independent studios. He previously wrote reviews and benchmarks for Tom's Hardware and contributed features to PC Gamer, covering everything from laptop testing to the economics of game development. Owen holds a Bachelor of Science in Electrical Engineering from the University of Texas at Austin and attends CES in Las Vegas, Computex in Taipei and the Game Developers Conference in San Francisco each year to meet chipmakers and developers. He writes for readers who want to know whether a product is worth the money, and he is not shy about saying when it is not.
All stories by Owen Castellanos (299)