Microsoft Pulls Out of Nscale UK Data Center Deal [2026]
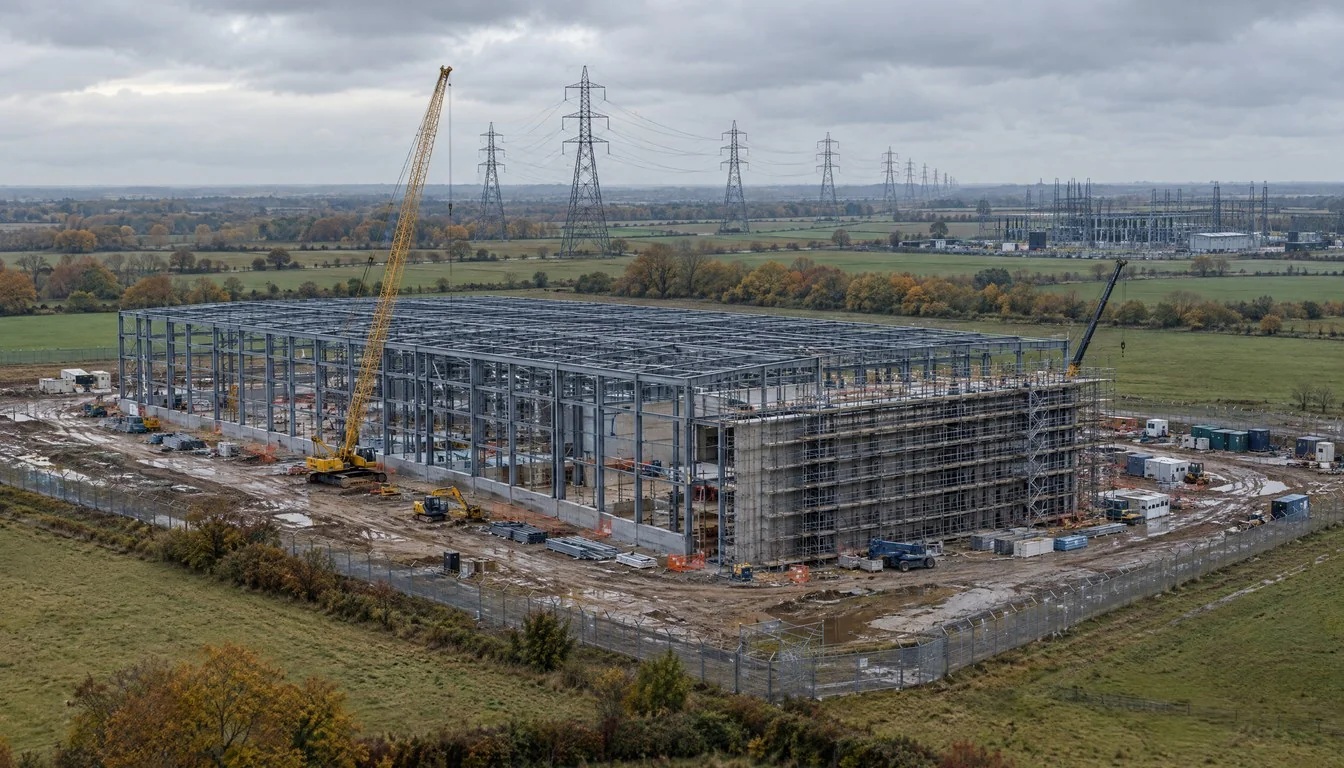
Microsoft has reportedly walked away from a major data center agreement with British AI infrastructure company Nscale, pulling out of a planned facility in Loughton, Essex, just weeks before the startup’s expected US stock market listing. The withdrawal, first reported by The Telegraph on October 18, 2026, strikes at the anchor tenant arrangement that was supposed to underpin Nscale’s first large-scale British AI data center and raises fresh doubts about how quickly the United Kingdom can actually deliver the power grid capacity that AI companies need.
The news matters well beyond one contract. Nscale had told investors in its initial public offering prospectus that Microsoft and Anthropic together account for roughly 85 percent of its contracted business, according to reporting on the filing. Losing Microsoft as the anchor tenant for the Loughton site, even if the broader relationship survives, exposes how concentrated the UK’s celebrated “neocloud” boom really is, and how fragile it becomes when a single hyperscaler reassesses its timeline.
Don't miss new tech stories on Google
Add TrendinTech once in the Google app and our stories appear in your news suggestions.
What Happened With the Microsoft Nscale Data Center Deal
According to The Telegraph’s October 18 report, Microsoft terminated its agreement to be the anchor tenant at Nscale’s proposed data center in Loughton, Essex, a site just northeast of London. Nscale had positioned the facility as its flagship UK project, the kind of deal that would prove British AI infrastructure could compete with sites in Virginia, Dublin, or the Nordics. Microsoft’s departure removes the commercial backbone of that specific project, even as Nscale insists its wider partnership with the Redmond giant continues.
The project had already been delayed repeatedly before this latest setback. Reports describe a recurring obstacle: getting enough electricity to the site on a timeline that matches the pace at which AI companies want to deploy GPU capacity. For a sector used to measuring progress in months, learning that a grid connection might not materialize until the 2030s is effectively a dealbreaker.
The Power Grid Problem Behind the Collapse
The reported root cause is not financing, chip supply, or construction, it is electricity. Authorities reportedly told Nscale that the Loughton facility might not get a reliable power supply until sometime in the 2030s. For a company trying to stand up a modern AI data center, where the entire business model depends on provisioning tens of thousands of GPUs as fast as possible, a decade-scale wait for grid capacity is not a delay, it is a cancellation in slow motion.
This is not an isolated British problem. Data center operators across Europe and parts of the United States have warned for the past two years that grid interconnection queues, not chip shortages, now represent the binding constraint on AI infrastructure growth. A facility can be fully permitted, fully financed, and fully equipped with racks ready to receive servers, and still sit dark because the local transmission network cannot deliver the hundreds of megawatts a modern AI campus requires. The Loughton case puts a specific, high-profile face on that abstract warning: a named hyperscaler, a named vendor, and a named town.
Nscale, for its part, is not conceding the site. A company spokesperson quoted by The Telegraph said the company remains “committed to both the Loughton project and the UK and we are exploring alternative power sources for the site, in addition to other expansion sites in the UK.” That statement, confirmed through Reuters wire coverage republished by Fidelity, suggests Nscale is looking at on-site generation, battery storage, or private power purchase arrangements rather than waiting on the public grid queue.
Nscale’s Response and the IPO Timing Problem
Timing makes this story sting more than a routine contract cancellation would. Nscale filed for a US initial public offering last month, and reports describe a proposed valuation that could reach roughly 35 billion dollars. Losing an anchor tenant commitment from one of your two largest customers, weeks before investors start reading the prospectus line by line, is about the worst moment such news could surface.
Nscale has tried to draw a sharp line between the Loughton setback and its overall relationship with Microsoft. A company spokesperson told The Telegraph that “our relationship with Microsoft remains strong and long-term, and this unfortunate London-wide grid issue has no impact on our other contracts.” That framing puts the blame squarely on the grid operator rather than on Microsoft’s appetite for Nscale’s capacity more broadly, a distinction that matters enormously for how IPO investors will price the stock.
Whether investors accept that framing is the real question. A prospectus that discloses 85 percent customer concentration in two buyers was always going to draw scrutiny. News that one of those two buyers has already pulled out of the company’s marquee domestic project, even with an explanation attached, gives skeptical analysts a concrete data point rather than a hypothetical risk factor. Expect the roadshow conversation to center heavily on diversification plans and on how fast Nscale can replace the Loughton capacity commitment with a site that actually has power.
Why Microsoft Walked Away
Neither Microsoft nor Nscale has given a detailed public explanation for the specific decision, and reports are explicit that no specific reason was provided beyond the general grid-delay context. That absence of an official rationale has not stopped industry observers from reading between the lines. Microsoft has spent the past two years racing to lock in GPU capacity across multiple continents through a mix of owned data centers, neocloud partnerships, and long-term power agreements. A site that cannot deliver electricity until the 2030s simply does not fit inside any version of that roadmap, regardless of how promising the underlying real estate or fiber connectivity might be.
It is also consistent with a broader pattern that has become visible across the hyperscaler world this year. Companies like Microsoft, Amazon, and Google have grown increasingly willing to walk away from or renegotiate data center commitments when the underlying infrastructure math stops working, even when doing so creates visible friction with a partner. The capital at stake in AI data centers is now large enough, and the competitive pressure from Anthropic’s, OpenAI’s, and Google’s own compute buildouts is intense enough, that hyperscalers are prioritizing deployable capacity over loyalty to any single site or vendor relationship.
How This Fits Microsoft’s Wider AI Infrastructure Strategy
Microsoft has been one of the most aggressive capital spenders in AI data center construction over the past two years, funding everything from its own hyperscale campuses to partnerships with specialized neoclouds built specifically to rent out GPU capacity on contract. Nscale was one piece of that diversified approach, alongside deals with other infrastructure providers designed to give Microsoft flexibility beyond its own owned and operated footprint.
That diversification strategy makes the Loughton withdrawal easier for Microsoft to absorb than it would be for a company with fewer alternatives. If a single neocloud site falls behind schedule, Microsoft can reportedly shift committed GPU volume elsewhere, whether to its own UK or European facilities, to other Nscale sites not affected by the London-area grid issue, or to entirely separate vendors. For Nscale, which is explicitly described in reporting as a smaller, newer entrant dependent on a concentrated customer base, the same setback carries much larger consequences.
Readers tracking the broader AI compute race have seen similar dynamics play out around model training capacity disputes, where providers like GitHub Copilot’s decision to drop three AI models reflected the same underlying pressure: infrastructure and capacity costs are forcing vendors to make hard tradeoffs even when customer-facing commitments are already public. The AI sector’s capital intensity means decisions once considered settled, whether a model lineup or a data center lease, are being revisited constantly.
Table: Key Facts in the Microsoft Nscale Withdrawal
| Detail | What’s reported |
|---|---|
| Company terminating the deal | Microsoft Corp. |
| Data center operator | Nscale |
| Site location | Loughton, Essex, United Kingdom |
| Microsoft’s original role | Anchor tenant |
| Reported cause | Grid connection delayed, possibly until the 2030s |
| Report date | October 18, 2026 |
| Reporting outlet | The Telegraph |
| Nscale’s two largest customers | Microsoft and Anthropic (approximately 85% of contracts) |
| Nscale’s stated position | Still committed to Loughton, exploring alternative power sources and other UK sites |
| Timing relative to IPO | Weeks before Nscale’s planned US stock market listing |
Nscale’s Business Model and Why Customer Concentration Matters
Nscale built its pitch to investors around being a specialized, AI-first alternative to the traditional hyperscalers, a company that could stand up GPU-dense data centers faster and more cheaply than Microsoft, Amazon, or Google could do for themselves. That pitch depends on landing a small number of very large anchor contracts, because the capital cost of a gigawatt-scale AI campus is too high to justify building speculatively for a diffuse base of smaller customers.
The tradeoff is concentration risk, and it is now playing out in public. When two customers account for 85 percent of contracted revenue, the health of the entire company effectively becomes a referendum on the continued goodwill and continued infrastructure needs of those two buyers. Microsoft and Anthropic both have enormous, independent reasons to keep buying AI compute, but neither is obligated to buy it from Nscale specifically, and neither is obligated to honor a commitment to a site that cannot deliver power on schedule.
This is a familiar pattern in capital-intensive infrastructure businesses, but it has rarely been tested this visibly in the AI data center sector, since most neocloud operators are still privately held and do not have to disclose customer concentration the way a prospectus requires. Nscale’s IPO filing effectively forced transparency that competitors have so far avoided, and that transparency is now generating headlines at the worst possible moment in the listing process.
Competitive Field: How Nscale Compares to Other Neoclouds
Nscale is part of a wave of specialized AI infrastructure providers, sometimes called neoclouds, that emerged over the past three years specifically to rent GPU capacity to AI labs and large enterprises without the overhead of running a full general-purpose cloud platform. Competitors in this space include CoreWeave in the United States, Lambda, and a handful of regional operators across Europe and Asia that have signed similar anchor-tenant arrangements with major AI labs and hyperscalers.
What differentiates Nscale’s situation is the specific combination of being UK-based, pursuing a near-term US listing, and depending so heavily on a single contested site for a meaningful share of its near-term growth story. Operators with geographically diversified footprints, or with contracts spread across more customers, are generally better insulated from exactly this kind of single-site, single-customer shock. The Loughton episode is likely to become a reference case other neoclouds point to when explaining to their own investors why geographic and customer diversification matters, even if it slows near-term growth.
Table: Neocloud Model Compared to Traditional Hyperscaler Data Centers
| Factor | Neocloud model (e.g. Nscale) | Hyperscaler-owned (e.g. Microsoft Azure) |
|---|---|---|
| Customer base | Concentrated, often 1-3 anchor tenants | Millions of diversified customers |
| Speed to deploy | Designed to be faster, AI-first builds | Slower, but backed by decades of grid relationships |
| Power procurement use | Limited, dependent on local grid timelines | Stronger, can negotiate directly with utilities at scale |
| Capital structure | Often reliant on anchor-tenant prepayments and IPO capital | Self-funded from existing cloud revenue |
| Risk if an anchor tenant exits | Severe, can threaten project viability | Minimal, internal capacity reallocated |
| Primary customers in this case | Microsoft, Anthropic | Internal Azure and Copilot workloads |
Historical Context: The UK’s Data Center Power Problem
Britain’s grid capacity constraints are not new, but AI has made them impossible to ignore. For years, data center developers in London and the surrounding commuter belt, including areas like Loughton in Essex, have warned that connection queues for new high-voltage supply can run into years, sometimes close to a decade, because of how the national transmission and distribution network allocates new capacity. Historically, this was a manageable problem for conventional data centers, which draw meaningfully less power per rack than today’s GPU-dense AI clusters.
AI changed the math entirely. A single modern AI training cluster can require as much electricity as a small town, and demand for that kind of capacity has grown far faster than the UK’s grid operators have been able to plan around. The result is a growing list of announced AI data center projects across the UK and Europe that look fully financed and fully designed on paper but remain stuck waiting for a literal cable to be run and energized. The Loughton situation is the most prominent example yet of that gap actually killing a named, high-profile hyperscaler commitment rather than simply delaying a groundbreaking ceremony.
The UK government has repeatedly signaled ambitions to position the country as a leading AI hub, a theme that has run through coverage of regulatory moves like the UK Competition and Markets Authority’s scrutiny of Microsoft’s business software dominance. Those ambitions now collide directly with the physical reality that grid upgrades move far slower than AI investment cycles, a tension that is likely to shape UK AI policy debates well into 2027.
Market Impact: What This Means for AI Infrastructure Investors
For investors evaluating Nscale’s upcoming IPO, the Loughton news forces a harder look at execution risk that goes beyond the usual AI infrastructure growth narrative. A company planning a roughly 35 billion dollar valuation needs its prospectus story to hold up under scrutiny, and “our largest customer walked away from our flagship domestic project due to a grid problem we did not fully control” is a difficult sentence to explain away in a roadshow, even with Nscale’s public reassurances about the relationship remaining intact.
More broadly, the episode is likely to push institutional investors toward demanding clearer disclosure from neocloud operators about power procurement timelines, not just chip supply agreements or customer letters of intent. Expect due diligence processes on future AI infrastructure IPOs to include specific questions about grid connection status, since this case demonstrates that a signed customer contract means little if the underlying site cannot physically receive the power needed to operate it.
There is also a read-through for utility and grid infrastructure investors. If AI data center demand keeps outpacing grid upgrade timelines in major markets like the UK, pressure will build on governments to fast-track transmission investment and on private capital to fund dedicated power generation for data centers, whether through on-site gas, battery storage, or direct renewable power purchase agreements. Nscale’s exploration of “alternative power sources” for Loughton is itself a preview of where much of the neocloud sector may be headed.
What Comes Next for Nscale and Microsoft
In the near term, watch for three things. First, whether Nscale secures an alternative power arrangement for Loughton quickly enough to keep the site alive in some form, or whether it quietly shelves the project in favor of other UK locations. Second, whether Microsoft publicly reaffirms its broader relationship with Nscale beyond the general statement already attributed to Nscale’s spokesperson, since Microsoft itself has not been quoted directly in reporting so far. Third, how Nscale’s IPO prospectus is amended or footnoted to address the Loughton development before the listing proceeds.
For the UK more broadly, the case is likely to intensify political pressure on grid operators and energy regulators to accelerate connection timelines for strategically important AI infrastructure projects, much as other industries have previously won expedited treatment for projects deemed nationally significant. Whether that pressure translates into faster permitting and construction, rather than just faster promises, will determine whether Britain can actually compete for the next wave of hyperscaler AI investment or continues losing anchor tenants to jurisdictions with more available power.
Predictions: Where This Story Goes From Here
- Nscale will likely announce a revised Loughton plan, an alternative UK site, or both within the next two to three months as it works to stabilize its IPO narrative.
- Microsoft will probably continue publicly describing its Nscale relationship as intact while quietly diversifying additional UK and European AI capacity commitments across multiple vendors.
- Expect at least one other UK or European neocloud operator to face similar public scrutiny over grid-connection timelines within the next six months, as investors apply the Loughton case as a due-diligence template.
- UK policymakers will likely announce new proposals aimed at fast-tracking grid connections for data centers classified as nationally significant infrastructure, following political pressure generated by this episode.
- Nscale’s IPO pricing, if the listing proceeds on its original timeline, will likely reflect a valuation discount tied directly to the customer concentration and execution risk this episode has highlighted.
Why This Story Matters Beyond One Contract
The Microsoft Nscale episode is a useful stress test for a narrative that has dominated tech coverage for two years: that AI infrastructure spending is effectively unlimited and unstoppable. The underlying demand for AI compute clearly remains enormous, as seen in continuing coverage of AI model races like Gemini 4 Argon’s head-to-head competition with Claude Opus 5.5 and the broader scramble among labs to secure training capacity. But demand alone does not guarantee that any single project, vendor, or site will get funded and built on schedule. Physical constraints, especially electricity, are reasserting themselves as the actual bottleneck, regardless of how much capital is chasing AI infrastructure deals.
That reassertion of physical limits is likely to be one of the defining AI infrastructure stories of the next two years, as more projects hit the same wall Nscale has hit in Loughton. Readers following the broader AI coding and infrastructure race, including coverage of tools like OpenCode 2.0’s expanded API access to more than 75 AI models, should expect the conversation to shift gradually from “which model is fastest” to “which company can actually power the data center running that model.”
It is also worth watching how this affects sentiment around other announced UK AI investments, including the kind of funding activity covered in reporting on AI startup funding rounds worldwide, since investors increasingly weigh infrastructure delivery risk alongside model and product risk when pricing AI-adjacent companies.
Frequently Asked Questions
What exactly did Microsoft do with the Nscale data center deal?
Microsoft reportedly terminated its agreement to be the anchor tenant at Nscale’s planned data center in Loughton, Essex, according to an October 18, 2026 report by The Telegraph.
Why did Microsoft reportedly pull out of the deal?
Reports point to repeated delays tied to electricity supply, with grid officials reportedly telling Nscale the site might not get a reliable power connection until the 2030s. Neither company has given a detailed official reason beyond this context.
What is Nscale?
Nscale is a British company building AI-focused data center infrastructure, sometimes described as a neocloud provider, that rents GPU computing capacity to large customers including Microsoft and Anthropic.
How much of Nscale’s business depends on Microsoft and Anthropic?
According to reporting on Nscale’s IPO prospectus, Microsoft and Anthropic together account for approximately 85 percent of the company’s contracted business.
Does this affect Nscale’s planned IPO?
Nscale filed for a US initial public offering last month, and the Loughton withdrawal surfaces weeks before the planned listing, which could affect investor sentiment and valuation discussions even though Nscale says its broader Microsoft relationship is unaffected.
Is Nscale abandoning the Loughton site?
No. A Nscale spokesperson told The Telegraph the company remains committed to the Loughton project and the UK, and is exploring alternative power sources along with other UK expansion sites.
Is this part of a wider UK data center power problem?
Yes. Grid connection delays have been a recurring issue for UK and European data center developers, and this case is one of the most visible examples of a hyperscaler commitment being affected by that constraint.
Has Microsoft commented directly on the withdrawal?
Public reporting so far has centered on Nscale’s statements responding to the situation. Microsoft has not been directly quoted with a detailed explanation in the reporting available at this time.
Related Coverage
Daniel Okafor
Daniel Okafor is the Senior AI Reporter at TrendinTech, where he covers large language models, machine learning research and the practical use of artificial intelligence across business and government. He has a particular interest in evaluation: how models are benchmarked, where those benchmarks fail and what that means for the companies betting on them.
All stories by Daniel Okafor (370)